By Donald Nyarota
Zimbabwe’s diamond sector, already burdened by local governance failures and worker exploitation, faces a perfect storm, mass layoffs, unpaid salaries, plummeting productivity, and the ripple effects of a historic global downturn in the diamond industry. A press statement released on 9 July by the Zimbabwe Diamond and Allied Minerals Workers Union (ZDAMWU) paints a bleak picture of a sector collapsing under the weight of both domestic mismanagement and international structural shifts.
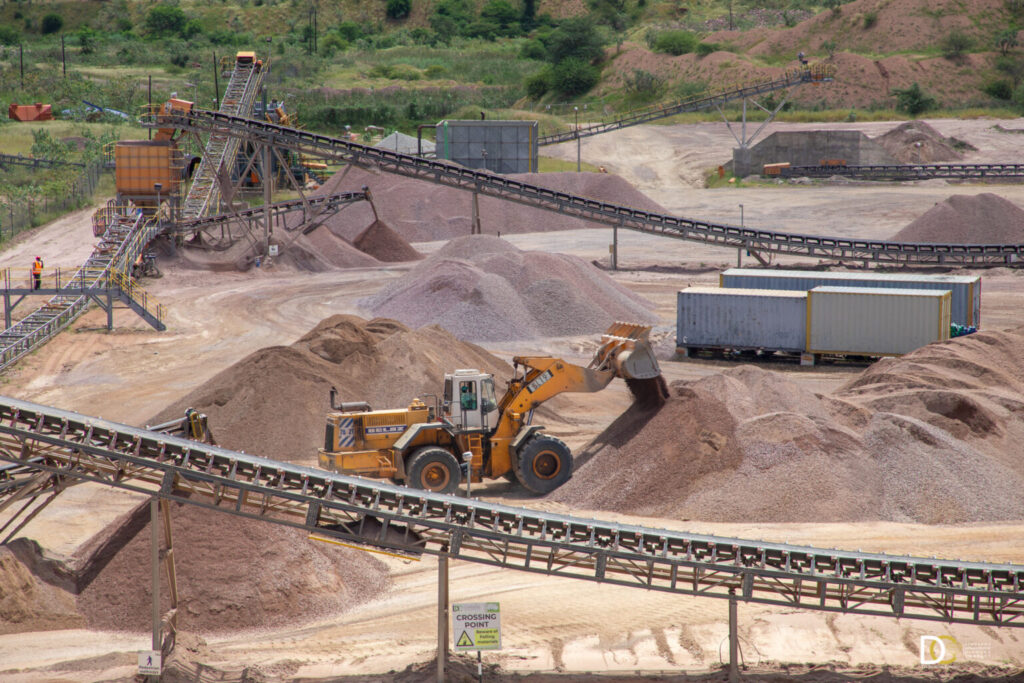
At the center of the crisis are three major mining operations, the Zimbabwe Consolidated Diamond Company (ZCDC), Anjin Investments, and Murowa Diamond, all embroiled in labour disputes that reflect the wider unravelling of an industry long plagued by opacity and inequity.
ZCDC is wholly owned by the Government of Zimbabwe, through private equity of Defold Mine (Pvt) Ltd, which has 100% shareholding. Anjin Investments is a joint venture between the Chinese company Anhui Foreign Economic Construction Group (AFECC) and the Zimbabwean military, represented through its investment arm, Matt Bronze. The two firms operate in Chiadzwa’s diamond fields in Manicaland province.
Murowa diamond mine is owned and operated by RZM Murowa (Private) Limited, a member of RioZim (a listed company), which operates in Mazvihwa, Midlands province. RioZim Limited is currently facing financial and operational challenges significantly impacted its operations, necessitating urgent measures to resolve the situation. The company’s difficulties have prompted negotiations with a potential lender and discussions with interested parties for a potential majority share purchase.
The Local Collapse: Retrenchments, Protests, and Wage Arrears
At ZCDC, the country’s flagship state-owned diamond company, up to 600 workers face retrenchment, with 295 already laid off through a so-called voluntary process. Yet none have received their severance packages. ZDAMWU warns that a mandatory retrenchment phase is now underway, despite union objections and in violation of fair labour standards.
“We condemn any forced or unfair retrenchment processes that violate workers’ rights and dignity,” said Justice Chinhema, ZDAMWU’s General Secretary. “The current situation exposes a disturbing lack of transparency and accountability in how these companies treat their workers.”
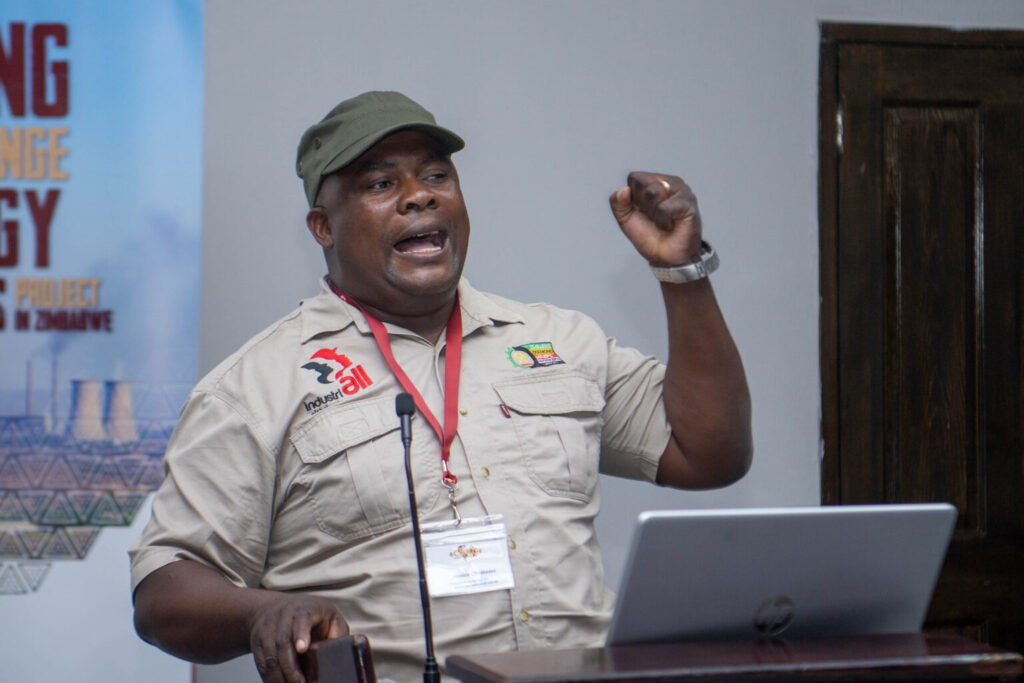
Justice Chinhema, general secretary of the Zimbabwe Diamond and Allied Minerals Workers Union (ZDAMWU)
Meanwhile, Anjin Investments, a Chinese-run firm operating in Marange, is under fire for failing to pay workers for four consecutive months, prompting spontaneous protests at company offices. At Murowa Diamonds, the crisis has deepened with workers staging a sit-in protest over five months of unpaid wages.
ZDAMWU is urging the government to intervene immediately to ensure payment of outstanding wages, halt unjust retrenchments, restore labour standards, and implement sector reforms that protect workers and promote sustainable, job-creating beneficiation.
A Global Industry in Freefall: The Bigger Picture
A wider, unprecedented global industry crisis exacerbates the local meltdown in Zimbabwe’s diamond industry. Since 2022, demand for natural diamonds has sharply declined, and polished diamond prices have collapsed, driven by multiple interlocking factors.
The diamond industry faces a systemic crisis, driven by the rapid growth of synthetic diamonds, which now account for 50% of the US engagement ring market, economic stagnation in China, and excessive inventory levels among major brands due to overbuying in 2022.
Unlike past crises, this one is rooted in deep-seated structural flaws, exposed by the rise of synthetic alternatives and a marketing vacuum. Unlike past crises linked to economic downturns (such as the 2008 global recession), the current crisis is systemic, with deep-rooted structural flaws exposed by the rise of synthetic alternatives and a marketing vacuum.
The Synthetic Disruption: A Crisis of Value and Identity
Synthetic diamonds, almost indistinguishable from natural ones but significantly cheaper, have disrupted the traditional luxury value proposition of mined diamonds. This coupled with an aggressive marketing campaign positioning lab-grown stones as more ethical and environmentally friendly, has successfully reshaped the consumer preferences of millennials. In contrast, natural-diamond producers have failed to develop a cohesive counter-narrative, leading to a sharp decline in demand, particularly for mid-range natural stones. Even traditional diamond giants like De Beers have diversified their portfolios with mixed results, to include synthetic diamonds.
One notable player that is pursuing this goal is the Swiss jeweller LOEV, which recently partnered with Ammil, a lab-grown diamond producer, to create the first Swiss-made jewellery collection of its kind. To appeal to environmentally-conscious consumers, they claim that their collection uses renewable sources of energy almost entirely – up to 90% – to produce these diamonds. Moreover, they are also appealing to the exclusiveness of the Swiss-made brand to promote rings that can be considered luxury goods.
As a result, inventory levels have surged, especially in India’s cutting and polishing centers, causing polished diamond prices to collapse, starting in mid-2022, and undermining the notion of natural diamonds as a reliable store of value. Furthermore, rough diamond prices remained artificially high until mid-2023, creating a widening profit gap that has severely impacted the manufacturing segment.
India’s Bottleneck: A Global Price Driver
India, home to about 90% of the world’s diamond cutting and polishing, plays a crucial role in the diamond price chain. However, reports show mounting inventories and high fixed costs, as Indian manufacturers are trapped between obligatory raw purchases and sluggish polished demand. It is a paradox that has led to a cycle of temporary production halts, as seen in October 2023 and again in 2024, which briefly stabilized prices, but manufacturers cannot sustain idle operations for long without risking their businesses. As a result, weak demand is triggering price cuts, further devaluing natural diamonds and eroding market confidence.
Zimbabwe’s Dilemma: Caught in the Crossfire
For Zimbabwe, a country struggling with fiscal instability, poor governance, and chronic underinvestment in beneficiation, the global diamond slump could not have come at a worse time. The government, a player in the sector, has failed to build resilient value chains, invest in local cutting and polishing, or ensure ethical, transparent practices, leaving the sector exposed. The development of a Gemology Centre cutting and polishing hub in Manicaland, has stalled since 2019. Meanwhile, worker conditions have deteriorated, and revenue from diamonds remains both unpredictable and inequitably distributed.
Despite its rich diamond resources, Zimbabwe’s industry fails to maximize value, leaving its workers vulnerable to exploitation. The country also exports 90% of its diamonds in rough form, capturing only 20% of the value, and lacks protections against market volatility and labour rights abuses, affecting an estimated 70% of its workforce. The sector is further constrained by escalating production costs, driven by inadequate utility access and high royalty rates of 10%, which negatively impact its overall performance.
These myriad challenges have weighed down the viability of mining projects.
The Ministry of Mines and Minerals Development is seeking to entrench a protectorate stance with the proposed designation of diamonds as a strategic mineral in a new bill gazetted for debate. Under the Second Schedule, diamonds are the only remaining strategic mineral, which will only be exploited by four companies, including ZCDC, through a joint venture arrangement with the state. Further requirements state that diamonds will be mandated to be polished and cut in the country before export in a move to bolster revenue generation from the gems.
The Way Forward: Structural Reform or Collapse
The crisis, both local and global, demands more than temporary fixes, a broader industry consensus, which requires rethinking the entire value chain. To address the crisis in the diamond sector, immediate local actions must be taken, including: The enforcement of labour laws and wage payments, an immediate halt to arbitrary retrenchments, and the establishment of inclusive social dialogue between unions, companies, and government. Furthermore, investment in downstream beneficiation is crucial to increase job creation and revenue retention.
Globally, the diamond trade must undergo significant reforms, including increased investment in marketing to reassert the value of natural diamonds, increasing market transparency, and aligning production with real demand. Additionally, the industry must address ethical concerns head-on, through such bodies as the Kimberly Process, by prioritizing traceability and responsible sourcing.
The convergence of local dysfunction and global disruption has brought Zimbabwe’s diamond sector to a breaking point. Without urgent action, not only will thousands of workers lose their livelihoods, but the broader economy will also miss a vital opportunity to benefit from one of its most precious resources.
Furthermore, investing in downstream beneficiation is vital to increase job creation and revenue retention, potentially boosting the sector’s contribution to the national GDP from 3% to 5%. As ZDAMWU warns, this is no longer just a workers’ issue; it is a national crisis that requires political will, policy reform, and a collective effort to restore value, dignity, and sustainability to Zimbabwe’s diamond industry.